To understand the outlook for both the US and Australian equity markets, it is important to first gain an understanding of the extraordinary events that have been happening in the US economy. We all know that one of the major things happening in the US is the investment in data centres. What is hard for Australians to appreciate is the enormous scale of that investment and the major effects it is having on the path of the US economy.
We can get a feel for this by looking at the numbers published by the US Bureau of Economic Analysis (BEA) on the path of the US economy so far this year. In the fourth quarter of 2025, US gross private investment grew at an annual rate of only 1.1%. Even within this, the investment areas that involve data centres saw equipment growth at an annual rate of 6.9%, while intellectual property products saw growth of 4.4% annualised.
These are two sectors which show the effects of growth in data centre demand, and both of these areas dramatically accelerated as we moved into the first quarter of 2026. In the first quarter of 2026, investment in equipment accelerated to a 15.5% annual rate, while intellectual property products accelerated to a growth rate of 15.6% annualised. This was a dramatic acceleration.
The level of investment in equipment continued at a 13.4% annual rate of growth in the second quarter of 2026, while intellectual property products grew at an annual rate of 9.2%. Estimates we have seen now show growth in the third quarter of 2026 running at a higher rate than we saw in the first quarter of 2026. In short, what we are seeing is historic levels of investment in the building of US data centres.
The result of this high level of investment growth is a high level of growth in US earnings. It also generates a high level of growth in US GDP. The BEA tells us that after growth of only 0.2% annualised in the fourth quarter of 2025, US GDP accelerated to a growth rate of 2.5% annualised in the first quarter of 2026, before growing by 2.2% annualised in the second quarter of 2026.
We estimate that it will grow at that rate or higher in the third quarter of 2026. This high level of growth means that US companies are making healthy corporate profits. When we put these levels of profits into our model of the US equities market, we find that our model explains 89.5% of the variation in the S&P 500.
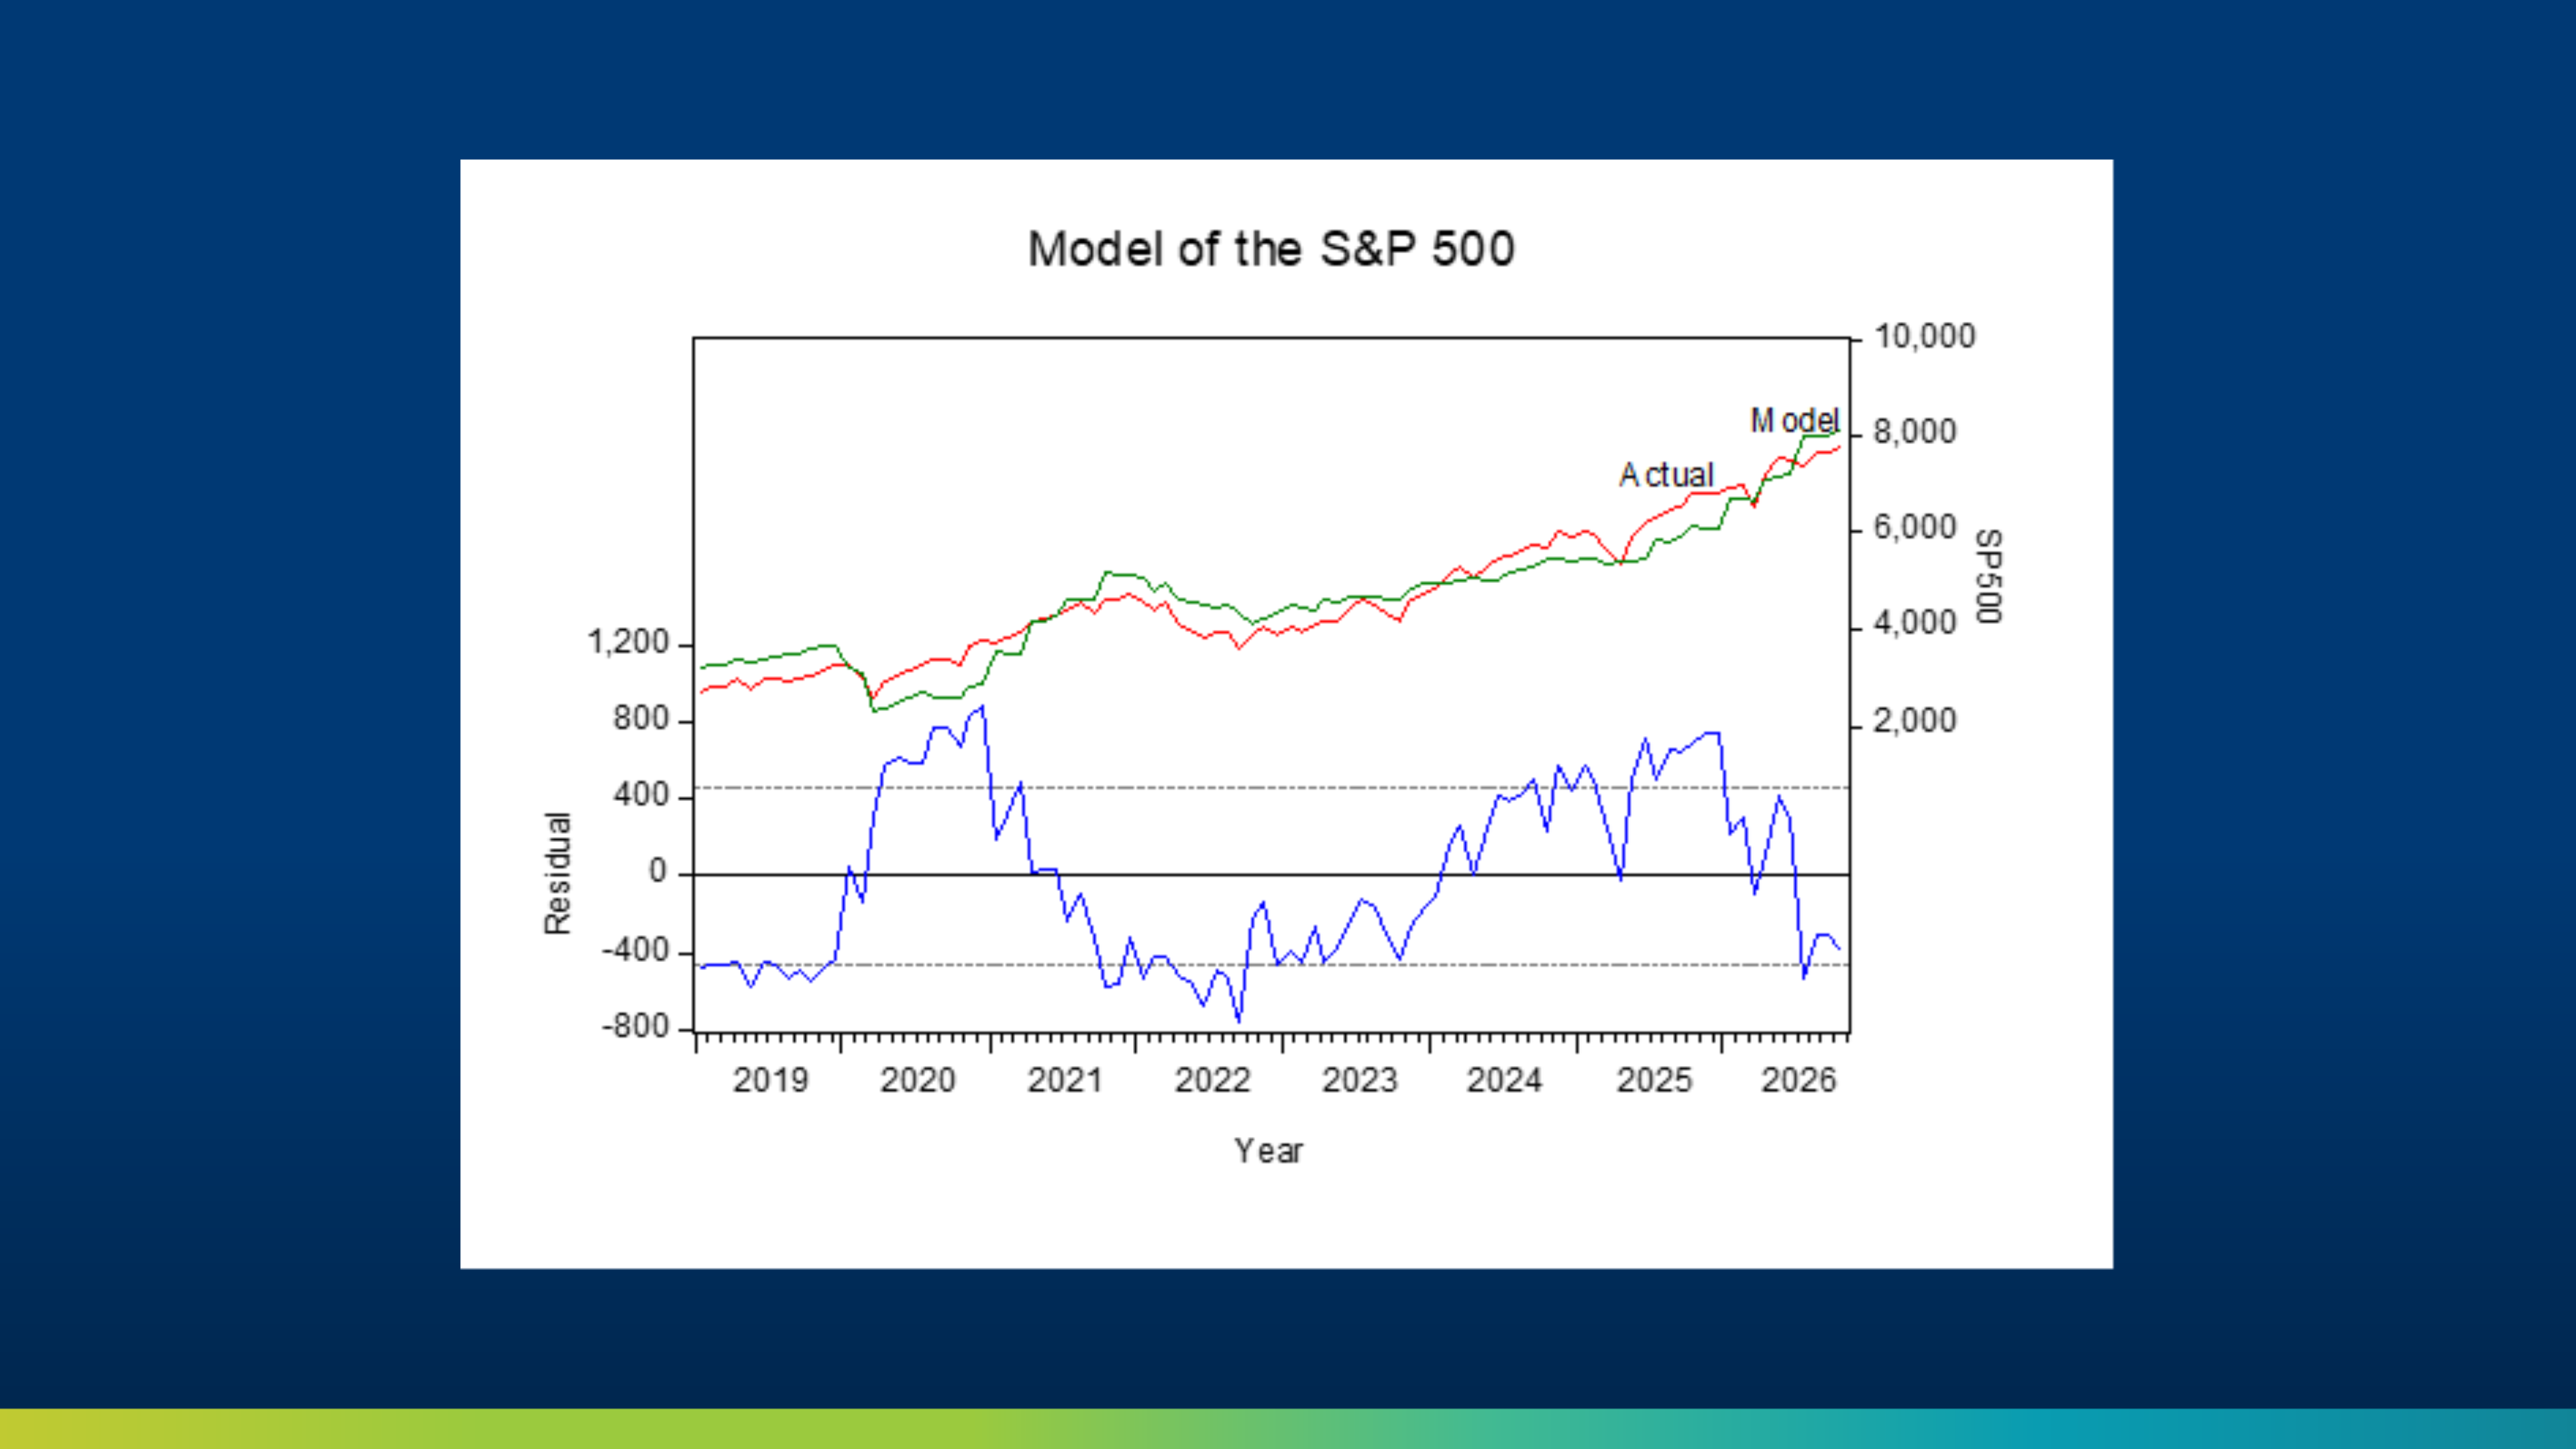
Since January 2019, the actual levels and our model are displayed in the chart above; also shown is the residual. This tells us that even though last year the S&P 500 was overbought, very strong growth in earnings in 2026, driven by a strong level of investment, has pushed the fair value of the S&P 500 to much higher levels.
On 8 October 2026, our model estimated a fair value for the S&P 500 of 8,194 points, which was 392 points higher than the actual traded level of 7,802 points. That means that right now, the S&P 500 appears undervalued in our model.
Interestingly, we think that the level of investment in data centres is approaching its ceiling. This means that, having achieved a very high rate of investment growth, it will continue around the current level through next year. This level of prosperity should continue for some quarters to come. As a result, US earnings should maintain their higher levels.
Compared to the titanic scale of this activity in the US economy, activity in the Australian economy is merely a minnow. Our market is likely to be swept up in US events. We may participate through a stronger Australian equities market as well, but we will do so only as a minor player.
Want to discuss how this impacts your portfolio?
DISCLAIMER: Information is of a general nature only. Before making any financial decisions, you should consult with an experienced professional to obtain advice specific to your circumstances.