Today we want to talk about a simple way of looking at growth in the Australian economy. It is a simple way, which leaves us with a handy indicator of where growth is going right now.
Everybody knows that we all work in the Australian economy. The important measure that's very helpful to economists is the number of hours worked.
Not that we work individually, but all of the hours that are worked in the Australian economy.
When you have a series of those hours, and the ABS does publish a series like that every month, and you add to that measure of hours worked a measure for productivity,
then what you've got is a very simple ,but very handy model of the year-on-year rate of growth in Australian GDP.
There are two measures that the statistician publishes of hours worked. One is the seasonally adjusted measure, but we prefer the trend measure because we think it's more stable.
So what we do is we get that data for hours worked, which is published every month as part of the survey of the labour force, and we construct a series of how it changes. To get our estimate of GDP, we add our estimate of productivity.
Now, there is a wide debate about what productivity is, but the measure that we use is very simple. We get the growth in hours worked, we generate the year-on-year rate of growth on that, and we add 0.7 to that, because that's our guess of where productivity is.
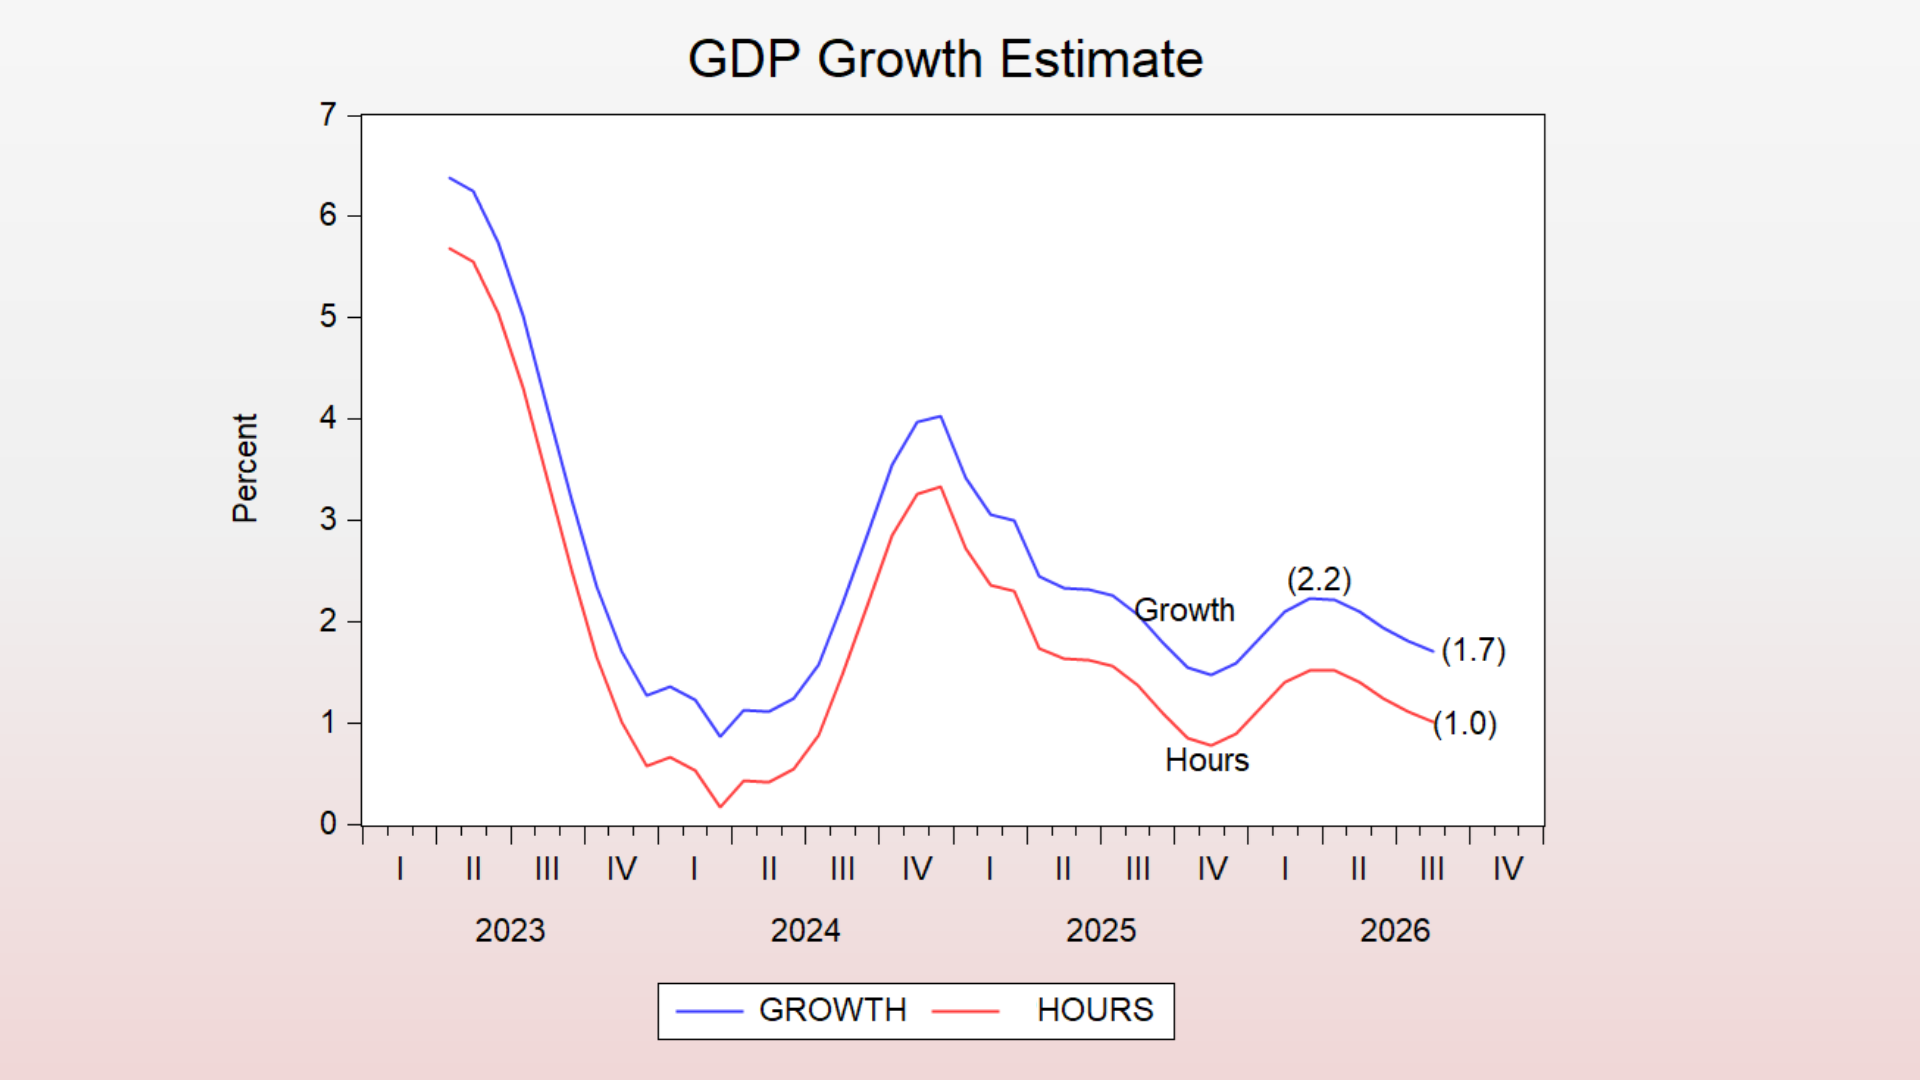
It is interesting to see where that takes our view of the Australian economy through last year and this year. When we got to the middle of last year, the Australian economy was decelerating. The rate of growth of hours worked, which was 1.6% for the year to June 2025, fell all the way down to 0.8 by the end of 2025. So in the second half of the year, that was when the Australian economy was slowing down. We remember the RBA took that opportunity in that period to actually reduce rates, because inflation at the same time was falling. Entirely different to now, when inflation is going up, of course.
So at the end of last year, the growth level of hours worked was about 0.9, which gave us an estimate that the Australian economy was growing at about 1.6%.
A lot of economists took that as their estimate for where growth was going to be, not just at that time, but through this year. We thought, that growth would be a lot stronger this year because we saw a turnaround in commodity prices.
So we thought there would be an acceleration and indeed there was.
Hours worked accelerated from 0.9% at the end of last year ,all the way up to a peak of 1.5% year on year by the end of the first quarter. It was a very rapid acceleration. Now, add that to our productivity estimate, and that gives you an outlook of GDP growth of 2.1 to 2.2%. So our growth rate estimate, therefore, for the Australian economy this year was 2.2%.
Since then, the Deputy Governor of the RBA, Andrew Hauser, when a growth rate of 2.1% was announced for the second quarter, thought that meant the economy was growing too rapidly. Our model told us that, for the year to June, growth in hours worked increased by 1.4%. And that gave us an estimate of growth in the economy of 2.1%. Indeed, the year-on-year growth rate in Australian GDP for the year to the second quarter was in fact 2.1%.
That was the high growth that Andrew Hauser was complaining about.
Since that time, however, growth in hours worked has declined. The most recent number, published only last week in September, was the number for August.
Here year-on-year growth in hours worked was 1%. That meant that the economy, we thought, was going to slow in the third quarter to a GDP growth rate of 1.7%.
Now, it's quite a long time until the growth estimate for the third quarter of this calendar year is going to be released, but we think it will come in pretty close to that 1.7% growth.
What that means is that the economy is slowing down. That's not going to stop the RBA from putting up rates, because what's not slowing down is inflation.
Sadly, that high inflation means that, in spite of the edge coming off growth in the Australian economy, the Australian cash rate is just going to have to be higher.
Want to discuss how this impacts your portfolio?
DISCLAIMER: Information is of a general nature only. Before making any financial decisions, you should consult with an experienced professional to obtain advice specific to your circumstances.